The article is separated into key sections to help break down the calculations.
Date & Month
The first two columns will show the period for which the lease activity is recorded by Date in (YYYY-MM) format, and the Month count.
Amortization/Operating Lease Expense & ROU Asset
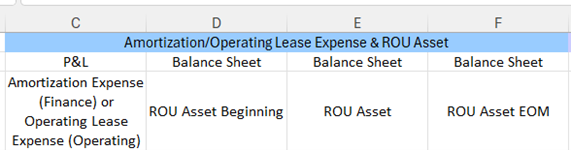
P&L Amortization Expense -Finance/ Operating Lease Expense- Operating (Column C):
Under ASC 842, operating lease expenses are recognized on a straight-line basis, while finance leases amortize the ROU Asset.
- Operating Lease: Calculated by dividing the Total Lease Payments by the lease term.
- Finance Lease: Determined as the ROU Asset Beginning Balance divided by the ROU Asset Life.
In the final month, the remaining amount ensures the ROU Asset value is reduced to $0.
ROU Asset Beginning (Column D):
Includes:
- Initial measurement of the Lease Liability (PV of future payments)
- Base lease payments made on or before the 15th of the lease start month
- Any Initial Direct Costs (if any)
- Subtracted: Incentives Received (if any)
ROU Asset (Column E):
The reduction in the ROU asset.
- Operating: Operating Lease Expense principal portion
- Finance: Amortization Expense principal portion
ROU Asset EOM (Column F):
Total of the ROU Asset at the end of the month, incorporating Amortization.
Interest Expense & Lease Liability
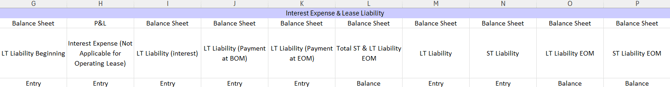
LT Liability Beginning (Column G):
- Present Value (PV) of lease payments: payments are discounted back to the start date. For more information, see Present Value Calculations in Crunchafi Lease Accounting.
- Payments from the 1st-15th of the month are excluded from PV calculations for base leases but included in ROU Asset. For more information, see our FAQ article: Why is the first payment missing from the Lease Liability?
- Transition leases include all payments in liability calculations but exclude pre-start date payments. For more information, visit What is a Transition Lease?
Interest Expense (Column H - Finance Leases):
- Monthly interest is calculated as: Previous EOM Liability Balance (Column l) - (Payments BOM (Column J) + EOM (Column K) included in LT Liability) x (Discount rate/12) .
LT Liability (Interest) (Column I):
Monthly accrual of total lease payment's interest portion.
LT Liability (Payment at BOM) (Column J):
Monthly payments processed at the beginning of the month (1st - 15th) that were included in the calculation of the lease liability.
LT Liability (Payment at EOM) (Column K):
Monthly payments processed at the end of the month (16th - EoM) that were included in the calculation of the lease liability.
Total ST & LT Liability (Column L):
The total remaining Lease Liability at the end of the month.
Long-Term Liabilities (Column M):
The portion of Long-Term Liability maturing within the next 12 months, per the standard that will be reclassified as current liability.
Short-Term Liabilities (Column N)
Current liability maturing within the next 12 months.
- Total amount of lease principal payments (Column J & K) plus Interest Expense (Column I) due within the next 12 months.
Long-Term Liabilities EOM (Column O):
Accumulated total of LT Lease Liability minus the reclassified ST Lease Liability as of the EOM.
Short-Term Liabilities EOM (Column P)
Accumulated total of ST Lease Liability as of the EOM.
Cash/AP & Other Entries
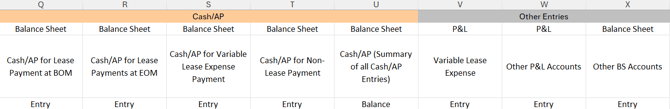
Cash/AP for Lease Payment at BOM (Column Q)
- Payment made between the 1st-15th of the month.
Cash/AP for Lease Payments at EOM (Column R)
- Payments made between 16th and the end of the month.
Cash/AP for Variable Lease Expense Payment (Column S) & Cash/AP for Non-Lease Payment (Column T):
- Payments made in the month recorded as a Variable and Non-lease expense.
Cash/AP (Summary of all Cash/AP Entries) (Column U):
- Reflects the sum of all cash payments for the month.
Variable and Non-Lease Payments (Column V to X):
Specific entries made for variable expenses and non-lease costs are reflected in dedicated GL accounts.